Fast HELOCs are great when a file is simple. When yours has a wrinkle (self-employed income, a low computer value, a trust, a condo), the automated answer is often no. Tell me what happened. I’ll look at your file personally and tell you straight whether there’s a better path.

Personally reviewed by Mike
Not an application·No credit pull·About 60 seconds
Fast HELOC programs run on automation: a computer home value, a quick credit check, and a narrow set of rules. When something doesn’t fit, the system doesn’t ask. It just says no.
Every one of these points to a different possible fix with a different lender. Starting over with another automated app usually gets the same answer.
In plain English, not lender jargon.
I’m a broker, so I’m not limited to one lender’s rules.
Ideally without touching your first mortgage, and without giving up future equity.
And if there isn’t a good path, I’ll tell you that too, before you spend more time and credit inquiries applying in the wrong places.
Not an application·No credit pull
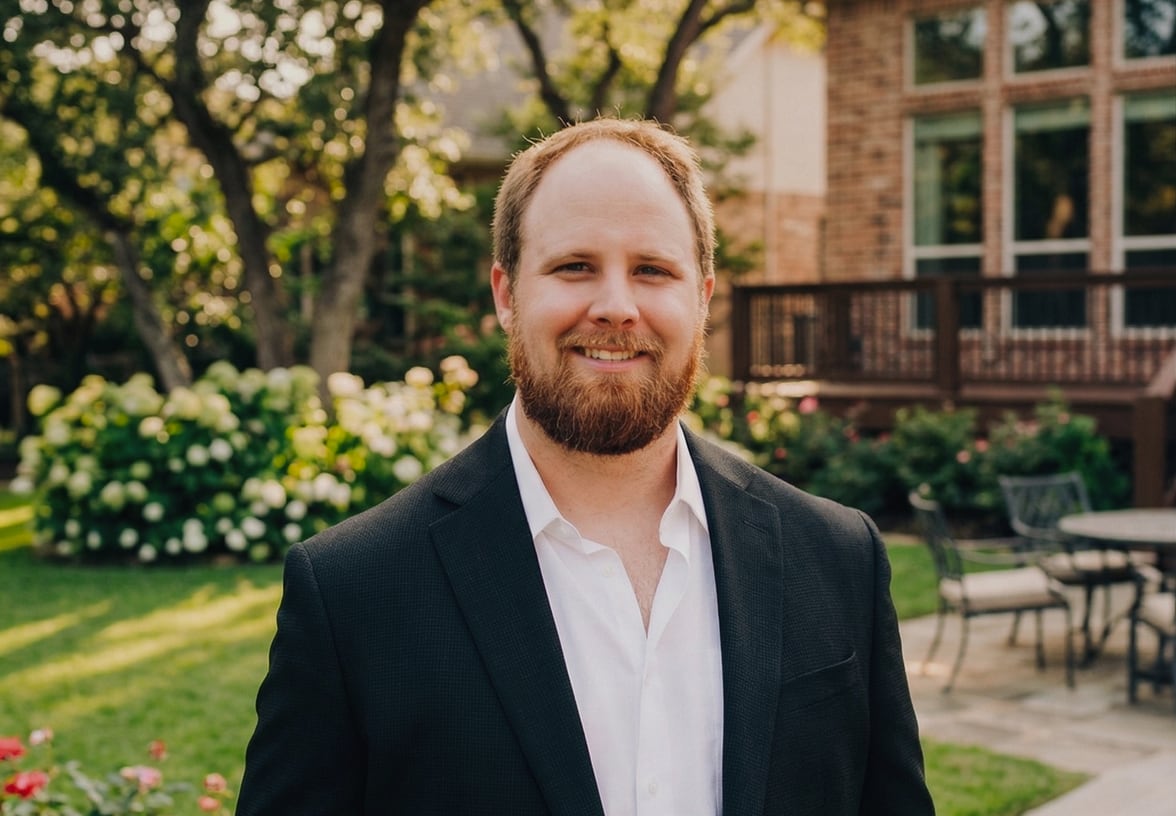
I’m Mike Pacheco. I started Qualified Home Loans in 2012 because I kept watching capable borrowers get told no. They weren’t unqualified. Nobody took the time to understand how they qualified.
I personally review every second-opinion request.
A self-employed business owner in the Los Angeles area needed to tap his home equity without touching his first mortgage. A fast online lender required tax returns for a loan his size, and after write-offs his returns didn’t show what his business really earns. So we qualified him on 12 months of business bank statements instead, and his fixed-rate second mortgage closed with his first mortgage left in place.
Client details changed for privacy. Every situation is different.
Qualified Home Loans NMLS #884457 · Mike Pacheco NMLS #236302
Or, at the very least, a clear answer and a plan instead of another automated no. That starts with one conversation.
Get My Second OpinionPrefer to talk now? Call Mike: 949-528-3967
